 Skip to main content
Budget 2026: all you need to know
The Chancellor John Healey delivered his first Budget on 28 October 2026. Despite considerable speculation ahead of the Budget, there were no changes to the main rates of Capital Gains Tax (CGT) or the annual exempt amount, although changes were announced to some of the CGT reliefs available to business owners.
The Government has also reversed its previously announced proposal to restrict Cash ISA subscriptions for individuals under age 65 to £12,000 a year from April 2027. This restriction will no longer go ahead.
There was, however, a further increase to the future rates of Income Tax applying to savings and property income. A two percentage point increase had already been announced from 6 April 2027, and the Budget added a further two percentage points. As a result, from 2027/28 the basic, higher and additional rates applying to savings and property income will be 24%, 44% and 49% respectively, compared with the current 20%, 40% and 45%. The Personal Savings Allowance and Starting Rate Band remain unchanged.
The summary below highlights the Budget announcements most relevant to financial planning. We have also included important measures announced previously which are due to take effect over the coming years, to provide a consolidated overview.
Pensions
State Pension Triple Lock changes from April 2030
Under the current Triple Lock, the basic and new State Pensions increase each year by the highest of average earnings growth, CPI inflation and 2.5%. From April 2030, the mechanism will change so that increases will instead be based on the highest of CPI inflation, 2.5%, and the amount needed to ensure the state pension keeps up with average earnings growth since the introduction of the new policy.
Pensions and IHT from 6 April 2027
Most unused pension funds and pension death benefits will fall within the estate for IHT purposes for deaths occurring on or after 6 April 2027. The Budget includes a minor technical amendment allowing those administering an estate to decide whether notional pension property is included in the general component of the estate or a separate component when calculating entitlement to the reduced 36% IHT rate where sufficient assets pass to charity.
Normal Minimum Pension Age rises to 57 from 6 April 2028
Subject to protected pension ages and other exceptions. This remains an important cash-flow consideration when planning retirement or bridging the period before pension benefits become accessible.
Pension salary sacrifice NIC restriction from 6 April 2029
Only the first £2,000 a year of employee pension contributions made through salary sacrifice will retain the NIC advantage. Salary-sacrificed pension contributions above £2,000 will attract employee and employer NIC. Importantly, this is not a £2,000 restriction on salary sacrifice or pension contributions themselves. Contributions can still exceed £2,000, but the NIC advantage on the excess will be lost.
Changes announced in this Budget
Two-year rule for pension death benefits
Legislation will remove the two-year rule under which otherwise tax-free pension and lump-sum death benefits could become taxable solely because payment (or designation) was made more than two years after the scheme administrator first knew, or could reasonably have been expected to know, of the member's death. The change applies to relevant payments made on or after 28 October 2026.
Terminal illness and pension access
Legislation will allow a serious ill-health lump sum to be paid where a member can reasonably be expected to live for less than one year. It will apply to uncrystallised rights irrespective of whether the member has reached age 75. Medical evidence will also be able to be provided by an overseas registered medical practitioner where the member lives in the country in which the practitioner practises. The change takes effect from Royal Assent of Finance Bill 2026-27.
Tax on excess lump-sum death benefits
The process for taxing lump-sum death benefits exceeding the deceased's available Lump Sum and Death Benefit Allowance (LSDBA) will change. Where a member dies before age 75, the excess will no longer be treated as pension income of the individual beneficiaries. Instead, a tax charge will be raised on each beneficiary's share of the excess by reference to their marginal Income Tax rate for the year in which the lump sum was paid. The legislation will also address the interaction between Income Tax and IHT. Different elements of the measure have different effective dates, including retrospective provisions applying to relevant lump sums paid from 6 April 2024.
Defined Benefit (DB) scheme surplus payments
From 6 April 2027, DB occupational pension schemes will be able to make direct payments of surplus assets to members where permitted by the scheme rules and subject to trustee discretion and statutory conditions. Qualifying payments will be taxed as pension income.
Taxation
Savings and property income
Savings Income Tax rates increase from 6 April 2027 to:
- 24% basic rate
- 44% higher rate
- 49% additional rate
- 49% trust rate for discretionary trusts
The Personal Savings Allowance and starting rate band for savings remain unchanged.
Investment bonds:
The savings-rate changes also have implications for the taxation of life assurance business and investment bond gains. Advisers will therefore need to revisit assumptions used when comparing onshore and offshore bonds from 2027/28.
Property Income Tax rates in England, Wales and Northern Ireland will increase from 6 April 2027 to:
- 24% basic rate
- 44% higher rate
- 49% additional rate
- 49% trust rate for discretionary trusts
Income Tax ordering rules:
Consequential changes from April 2027 will affect how allowances and reliefs are allocated between different categories of income following the introduction of separate savings and property rates.
Pension Tax Allowance
- New Pension Tax Allowance from 6 April 2027: this is intended to prevent pensioners whose total income is no more than the full new State Pension from having to pay small amounts of tax through Simple Assessment. It will operate in 2027/28, 2028/29 and 2029/30.
- For 2027/28, the threshold below which the full allowance applies is £13,037 and it is fully withdrawn at £13,319. The allowance is withdrawn at £1 for every £3 of income above £13,037.
Property
- High Value Council Tax Surcharge: from April 2028, an additional charge will apply to residential properties in England valued at £2 million or more. This will be relevant for people who are property-rich but potentially income- or cash-poor in retirement.
Thresholds
- Frozen thresholds and allowances: advisers should continue to factor fiscal drag into longer-term financial planning, including the continuing freezes affecting Income Tax thresholds, the IHT nil-rate bands and ISA limits.
CGT and business owners
- Business Asset Disposal Relief (BADR): the lifetime limit will reduce from £1 million to £500,000 for qualifying disposals from 6 April 2027. This could make the timing of business disposals particularly important for qualifying clients.
- Founders' Relief: a new relief will provide a 10% CGT rate on up to £10 million of qualifying lifetime gains on eligible disposals of shares or securities from 6 April 2027. It is targeted at founders and early investors who have made a significant long-term contribution to qualifying high-growth, innovative UK companies.
- Trading Allowance: increases from £1,000 to £3,000 from 6 April 2027. The Self Assessment trading income reporting threshold will also increase to £3,000.
Employment taxation
Mandatory payrolling of Benefits in Kind: the introduction will be phased:
- Company cars and vans, car and van fuel and medical benefits from 6 April 2027
- Most other Benefits in Kind from 6 April 2028
Investments and ISAs
- Cash ISA restriction scrapped: the previously announced proposal to restrict Cash ISA subscriptions for individuals under age 65 to £12,000 a year from 6 April 2027 will no longer proceed.
- Starter Investment ISA: the Government will work with the investment industry on a possible new ISA incentive for people investing in a Stocks & Shares ISA for the first time. The detailed design has yet to be developed.
- Lifetime ISA: the withdrawal charge where a first home costs more than the existing £450,000 LISA property limit will be reduced from 25% to 20%. The 25% charge will continue to apply to other unauthorised withdrawals.
- First Time Buyer ISA: a new product will replace the Lifetime ISA for new savers. It will provide a 25% Government bonus on the final account balance, subject to a maximum bonus of £20,000, towards the purchase of a first home worth up to £450,000. Existing LISA holders will be able to continue contributing to and using their accounts under the existing rules. Launch is scheduled for April 2029.
- Help to Save: the scheme will be made permanent and eligibility widened from April 2028 to include Universal Credit claimants receiving the child element, caring element or both.
- Employee share schemes: changes will be made to both the CSOP and EMI regimes from 6 April 2027. In particular, the individual CSOP option limit will increase to £120,000, alongside other changes to the operation of the two schemes.
Other announcements include:
- A new equity-loan scheme for first-time buyers
- Increases to the National Minimum Wage and National Living Wage from April 2027
- A further freeze in fuel duty
- Changes to domestic energy charges
- Future reform of the Carer's Allowance earnings cliff edge
- The introduction of statutory parental pay for eligible self-employed individuals
If you’d like to know how the budget may impact your financial plans, why not get in touch and speak to one of our advisers today for a free initial consultation.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate estate planning, cash flow panning, trust or tax advice.
The Budget 2026: key changes to tax, pensions and ISAs
After far fewer leaks than previous years, Chancellor John Healey delivered his first Budget this afternoon.
The key changes were:
Savings and Property Tax
- An additional 2% increase to Savings and Property Tax from April 2027:
- Savings and property income tax were due to increase from 20%, 40% and 45% for basic, higher and additional rate taxpayers to 22%, 42% and 47% with effect from April 2027.
- They will now increase by an additional 2% to 24%, 44% and 49% for basic, higher and additional rate taxpayers with effect from April 2027.
- This will impact landlords and those with cash in the bank outside ISAs whose interest exceeds their Personal Savings Allowance.
- This also impacts Offshore Bond owners as Chargeable Gains are treated as savings income.
Business Asset Disposal Relief
- Which entitles qualifying business owners to a reduced capital gains tax rate of 18%, will have its lifetime limit reduced from £1,000,000 to £500,000 from April 2027. However, Founders’ Relief will entitle those who qualify, to a capital gains tax rate of 10% up to a lifetime limit of £10,000,000
Cash ISA
- The Cash ISA allowance will no longer be limited to £12,000 with effect from April 2027 for under 65s - this will remain at £20,000. Plans to tax cash and cash like investments within stocks and shares ISAs have also been scrapped.
Pension Tax Allowance
- The full State Pension will increase to £13,036 in April 2027 – it has been confirmed that pensioners over the State Pension Age with total income of £13,037 or less will not pay tax on the amount above the personal income tax allowance of £12,570. Pensioners with income between £13,037 and £13,319 (not just from State Pension) will benefit from a tapered Pension Tax Allowance on a 3:1 reducing scale. The allowance will be fully extinguished once income exceeds £13,319.
Lifetime ISA
- Penalty for accessing the Lifetime ISA to buy a house above the limit of £450,000 will be reduced from 25% to 20%. This means investors using the Lifetime ISA for its intended purpose will always at least get out what they put in (given the 25% bonus when funds are put into the ISA). The penalty will remain at 25% for other unauthorised withdrawals. A new ‘Starter ISA’ will also be introduced for first time investors, though details in respect of this were limited.
- Pension administration changes. Measures will be introduced immediately to preserve the entitlement to tax free benefits to nominated beneficiaries of pension funds, if the administration of the estate takes longer than two years from the date the pension scheme administrator is informed that the member has died. In addition, from April 2027, the collection of income tax on excess lump sum payments from pensions will be taken out of the income tax regime and a standalone tax collection process will replace it.
In terms of market reaction, at the time of writing gilt yields remained broadly unchanged and UK bank shares rose as a result of the announcement of a bank tax increase of 3% for 15 months (given this was not as severe as analysts had feared).
In summary, although the impact of the above on many people may be limited, the impact of frozen tax bandings will continue to affect millions of households. Having already been frozen until 2031, there were no further extensions to the freeze, but with UK CPI inflation currently 3.5% in September 2026, more and more taxpayers will move into higher rates of tax, whether that be 20%, 40%, 45% or 60%, even if they only receive inflationary increases to their pay.
The Budget was mixed news for savers, with the proposed reduction in the Cash ISA allowance being scrapped, but the tax on savings will now increase by 4% in April 2027. For business owners, the lifetime limit for Business Asset Disposal Relief being reduced to £500,000 is disappointing, but Founders’ Relief giving those who are entitled to the relief a reduced rate of 10% up to £10,000,000 will be welcomed. Landlords will be disappointed to see the tax they pay on rental income increasing by 4% (rather than 2%) in April, but rumoured increases to the standard rates of capital gains tax did not materialise.
To understand how the changes affect your financial plan, please get in touch for a free initial consultation to see if we can help.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate estate planning or tax advice.
Budget rumours? Don't panic.
It is not long until Chancellor John Healey’s first budget on 28 October 2026 and you may be wondering if you need to take any action ahead of this.
Newspaper speculation ahead of previous budgets has been rife, with rumours that tax free cash entitlements will be reduced seeming to surface around this time every year. Some pension holders seem to have been taken in by this speculation in previous years; a recent Sky News article revealed £91.2bn was withdrawn from pensions accessed for the first time in 2025/26, up from £53.6bn in 2023/24. However, some people may be regretting their decision to take money out of their pension, given they may have moved funds from a tax free environment within their pension into a taxable environment outside it.
Arrange your free initial consultation
Pensions minister Torsten Bell clearly finds the speculation unhelpful, describing misleading stories as ‘disgraceful’ and ‘garbage’ in a recent Citywire article.
Even if there are no changes to tax free cash entitlements announced in the budget, we are getting closer to the implementation date for a big pension change that has already been announced; that defined contribution pensions will form part of estates for inheritance tax (IHT) purposes from April 2027. Pensions should be reviewed ahead of this, specifically:
- The nomination of beneficiaries for pensions - if a married couple are planning to leave their pension to their children rather than each other, this could become tax inefficient in April 2027.
- The interaction between pension nominations and wills - especially when these are not being left to the same beneficiary. As inheritance tax will be proportioned between the pension and the estate, the net amounts each beneficiary receives may change overnight on 5 April 2027.
- Gifting to charities – again the best way to do this may change. Estates benefit from a reduced inheritance tax rate of 36% when over 10% of the taxable net estate is left to charity, but pension death benefits from April may be subject to IHT and income tax, so it could be the case that leaving part of the pension to charity rather than part of the rest of the estate may become the better option.
However, those aged under 75 who are married or in civil partnership should not panic, as upon their death they can leave their pension to their spouse/civil partner under the spousal exemption and their spouse/civil partner can in turn draw from the pension tax free. Longer term however, consideration could be given if appropriate, to drawing from the pension to create excess income that can be gifted away under the regular gifts out of surplus income IHT exemption as the individual approaches age 75, at which point the tax rules change.
In terms of changes that could be announced:
- Prime Minister Andy Burnham has signposted a new ‘Your First Home’ scheme to help first time buyers get on the housing ladder.
- There are rumours that capital gains tax (CGT) could be increased. The level and timing of the increase would be important if this does happen, as there are question marks over the increased revenue that is actually raised by increasing CGT, given individuals can choose to hold onto assets and not sell them if increases to CGT rates are significant. However, if a change is announced to take effect in April 2027, this gives individuals the chance to sell assets before the higher rate kicks in which could lead to an increase in activity.
- As has been the case in previous years, the chancellor has the option to freeze tax bandings further into the future.
To summarise, Torsten Bell’s comments indicate he is hoping not to see the same level of pre-budget speculation as previous years and investors have often seen sub-optimal outcomes after making decisions based on speculation alone. Therefore, we will need to wait until after the budget to decide if any action is required as a result of any newly announced changes, alongside already known:
- Fiscal drag caused by frozen tax thresholds until 2031
- Upcoming increases to property income and savings tax rates in April 2027
- Cash ISA changes which will limit contributions from next year and mean that individuals looking to transfer their Stocks and Shares ISA into Cash ISAs must do so by April 2027
- Mansion tax due to take effect in April 2028
- Salary sacrifice National Insurance saving contribution limit of £2,000 to take effect from April 2029
If you would like to discuss the implications of the upcoming changes, please contact get in touch to see how we can help.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate estate planning, wills or tax advice.
A pension is a long-term investment not normally accessible until age 55 (57 from April 2028 unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up which would have an impact on the level of pension benefits available. Your pension income could also be affected by the interest rates at the time you take your benefits.
UK State Pensions triple lock to be scrapped
Following the Labour Conference in Liverpool, the state pensions triple lock will be scrapped in place of a double lock, according to prime minister Andy Burnham.
Burnham explained that from April 2030, the state pension would continue to rise each year by 2.5% or inflation, whichever is highest, but would no longer be matching earnings – the original third guarantee of the triple lock.
‘It will hold its value relative to earnings over time so that pensioners will always share in the rising prosperity of the nation. This change will generate significant savings, which we will use to build up our own National Care Service,’ Burnham told the Conference.
Burnham went on to compare the policy as one that was as significant as the ‘creation of the NHS itself’.
The triple lock is considered a gold standard for pensioners in the UK, which represent a large voter base, and as such governments have been reluctant to touch it despite a heated debate continuing around its fairness after so many years since its introduction by the Conservative-Liberal Democrat coalition government back in 2011.
Regardless of which side of the debate people fall on, it is clear that the scrapping of the triple lock represents a bold move by Burnham’s government.
"Retaining the inflation link will be comforting to current and future pensioners and if giving up the earnings link provides savings which can be directed towards the chronically underfunded care system then this will be welcomed by many. However, the devil is always in the detail and we eagerly await the promised detail in the next Parliament." – Jane Reade, Head of Financial Planning at The Private Office (TPO).
The 'Triple Lock' explained
The ‘triple lock’ refers to a well-known state pensions policy that ensures state pensions rise every year by either the average earnings growth, inflation (as measured by the Consumer Prices Index) or a flat 2.5% - whichever is highest that year, hence the name ‘triple’ lock.
It was designed in principle to make sure that state pension value would always have the best growth outcome each year for pensioners. The guarantee that the highest of the three will be what pensions grow against ensures that savers have three layers of protection against inflation. This is incredibly important in maintaining a level of healthy financial security for those relying on their pensions, as it guarantees growth irrespective of how volatile the economy becomes.
If you want to find out more about retirement planning, why not give us a call on 0333 323 9065 or book a free non-committal initial consultation with one of our chartered advisers to find out how we might be able to help you.
Arrange a free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
Back to the future for pensions
After 40 years in the industry, I will be hanging up my boots at the end of the year and taking up a new career on the golf course.
To say that I’ve seen a few changes in that time is an understatement but now, at the end of my career, I’ll take one last spin in the DeLorean and look at the twists and turns that pensions legislation has taken over the last four decades and how that has affected my clients.
Arrange your free initial consultation
The first thing I’d like to say is to offer my sympathies to the general public who have been subjected to rules and complexities which should really be the preserve of rocket science. The opaqueness of pensions has been a disservice to the consumer and for many, this lack of clarity has resulted in rejection. I really don’t blame anyone for this. I have a similar reaction if, for instance, I’m trying to work out which mobile phone package is best. In the end, there is a tendency to turn your back on the whole subject for fear of doing the wrong thing.
But let me make one thing clear. Pensions are, and always have been, the most tax efficient means of saving for retirement.
Stepping back to 1987
If I set my clock to 1987 and step out of my time machine, apart from the padded shoulders, I’m struck by the fact that full tax relief is available on contributions (up to a limit). This is still the case now and if I can say what the most common question clients ask just before a budget it’s “Do you think they will take away higher rate tax relief on pensions?”. Here I am, nearly 40 years later and this highly attractive property of pensions remains intact, yet I expect one last wave of this question before this, my final budget as an adviser.
Tax relief was even more attractive back then because income tax was higher. Who would turn their nose up at the opportunity to invest £40 and for it to be immediately worth £100 (the higher rate of income tax was 60% in 1987)? Many did though. Maybe they thought it was too good to be true. But it was!
In those days, personal pensions were mostly found amongst the self-employed as employed people often enjoyed final salary pension schemes. Over the years, final salary schemes have been culled from the private sector (they’re simply too expensive for employers to run). Now, unless you’re in the public sector, final salary pension schemes are like hens’ teeth.
What happened to pensions from 1995
Let’s get back in the DeLorean and get out in 1995. Until then personal pensions were restricted in that you had to buy an annuity when you retired. This was all very well and meant people didn’t have to worry about investment returns. Annuity rates were also high (although this really only reflected the fact that we had double digit inflation). By 1995, however, rates were reducing and there was growing unrest driven by the prospect of parting with your pension pot in exchange for a low annuity return. So, under John Major’s government, income drawdown was introduced and for the first time pension holders were allowed to keep their funds invested and take an income (within upper and lower limits). As gilt rates (and annuity rates) continued to tumble, we never looked back and drawdown was here to stay (albeit with some horror stories around high-risk portfolios suffering in subsequent market crashes).
Things bumbled along fairly uneventfully for the next twenty years but, in all this time, pensions were never attractive from an estate planning point of view, and nobody ever thought of them in this way. There were all sorts of complex rules which I have no intention of repeating here but, in essence, if pensions were left to anyone other than a spouse there was punitive tax. It was only when George Osborne announced pensions freedom in 2015 that the idea of pensions ‘cascading’ down the generations was invented. Before George, pension funds attracted a fairly hefty tax on death of 55%. Earlier than that and it could have been more, up to 82% in some circumstances. All of a sudden, there was no tax at all and pension funds, particularly for the very wealthy, were now parked for future generations. Furthermore, you could take the whole fund as drawdown. There was a lot of talk about Lambourghinis but, in truth, no one really wanted to draw out so much that they were subject to higher rate income tax.
Then came the Budget in 2024
Which brings us to the present and in 2024 Rachel Reeves announced that pensions would be subject to Inheritance Tax from 2027. Let’s put this into perspective and compare the taxation of a personal pension from 2014 to a pension in 2027. Let’s say leave it to your children as pensions passing to spouses is exempt from IHT. In 2014 it would have been subject to a 55% tax (if in drawdown) so they would end up with 45% of the fund. In 2027 there will be IHT, say 40% if the rest of the estate is substantial enough to use up the Nil Rate Band. This means that 60% is inherited but this, in turn, could be subject to income tax if they die after the age of 75. Let’s say the children are basic rate taxpayers. This means they will inherit, after tax, 48% of the fund compared to 45% in 2014.
There are, of course, situations where it is more punitive now (particularly if the children are higher rate) but the point is that in 2027 most people will be in a similar situation to tax legislation of 2014.
Will the government take away tax-free cash on pensions?
I think the second most common question I’ve had over the forty years is “Will they take away the tax free cash?”. True, it has been capped to the distinctly catchy number of £268,275 but, for most, it still stands at 25% of the fund. Will it be reduced further? Alas, I cannot go into the future, only the past. If I could have, I wouldn’t be here, would I? So, your guess is as good as mine.
In the final analysis, I would say that pensions are more attractive now than they were forty years ago. They are more flexible. Pensions are still inheritable, albeit distinctly less attractive from 2027. They are also cheaper to run. In the 80s most pensions were only available from insurance companies and charges were punitive. These days, plans are cleaner and don’t have initial charges. There is also much more choice of investment, not just a few vanilla funds. Drawdown is definitely a huge advantage, removing the compulsion to buy annuities. I should mention that you still can buy annuities and people still do, in certain circumstances. You could even have both annuity and drawdown.
But with more flexibility comes more responsibility. Good advice is absolutely essential, particularly when in drawdown. The greatest danger to any fund, from which meaningful withdrawals are being made, is something called Sequence Risk. This is the damaging effect on a portfolio if it is all invested in risk funds, and withdrawals are taken at the bottom of the market. A good adviser will recommend holding different risks for different timescales to negate this risk.
So, it’s time for me to forget about the past and buckle into the DeLorean to see what the future holds. I will now become a client of TPO and will see where the road takes us although, as Emmet Brown said “Where we’re going Marty, we don’t need roads”.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The information contained in this article is based on our understanding of legislation, whether proposed or in force, and market practice at the time of writing. Levels, bases and reliefs from taxation may be subject to change.
A pension is a long-term investment not normally accessible until age 55 (57 from April 2028 unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up which would have an impact on the level of pension benefits available. Your pension income could also be affected by the interest rates at the time you take your benefits.
The Financial Conduct Authority (FCA) does not regulate cash flow planning, estate planning, tax or trust advice.
Are you prepared to die?
Passing away without adequate preparation carries a heavy price tag. Beyond the obvious costs of a memorial service or burial, families face substantial hidden financial and emotional burdens when they overlook proper estate planning. Key oversights such as omitting a valid Will, failing to register a Lasting Power of Attorney, leaving cohabiting partners without legal protection, or leaving financial gifts incomplete can inevitably increase the strain on grieving loved ones.
Research we recently conducted, alongside government and industry data, shows just how widespread this unpreparedness is in the UK – and how much it can cost, in time, money and stress, when families are left to work it out on their own.
Arrange your free initial consultation
How prepared are we, really?
On paper, most people know they should plan ahead. In practice, most haven't. A study by the Money and Pensions Service revealed that 56% of adults in the UK lack a will, with 53% of individuals aged 50–64 falling into this category – an age group where concerns about death and incapacity shift from distant thoughts to a closer possibility. This is also the period of time often referred to as “Sniper's Alley”, when people face a sharply increasing risk of serious health conditions. Without a will, the law decides who inherits, not the person who died – and the rules rarely match what people actually intended.
The preparedness gap extends to digital assets too. A survey by consumer group Which? found that 76% of people have left no plan for what happens to their digital assets when they die. This is especially concerning when finances are involved, with research from Finder, a financial comparison and consumer education platform, estimating that 50.1 million people in the UK now use some form of online or remote banking; that's 91% of the adult population. With many having a digital footprint spanning multiple logins, accounts and portals, often with no record of them held anywhere accessible, for families trying to settle an estate, tracking down that information can add weeks of stress on top of grief.
The gap is even wider when it comes to understanding legal protection within relationships. A Ministry of Justice consultation found that 47% of people in England and Wales believe "common law marriage" exists and gives legal protection after a set number of years together. It doesn’t and never has. With 3.5 million people now cohabiting outside marriage or a civil partnership, and fewer than half of UK adults married or in a civil partnership, that misconception leaves millions exposed. Under current intestacy rules, an unmarried partner has no automatic right to inherit anything from their partner's estate, regardless of how long they lived together or how finances were shared - a protection that at least the children can receive.
Without a will, even a decades-long partnership offers no legal protection. It is one of the starkest examples of what being unprepared can cost the people you leave behind. Even if a will does leave everything to an unmarried partner, there is no Inheritance Tax (IHT) spousal exemption, so IHT would need to be paid, unlike when assets are left to a spouse or civil partner, when there is no IHT payable.
The Private Office's (TPO) own survey of 2,126 UK adults*, mostly aged 45 and over, found that gifting early is desirable. The overwhelming majority, 80.7%, believe wealth should be passed on to the next generation during their lifetime rather than left to inheritance – 67.9% see helping with a first home as the moment support matters most.
Yet many hold back. Retirement security and long-term care costs together account for over half of the concerns people give when asked what stops them from gifting more or gifting at all, demonstrating that financial uncertainty in later life remains the biggest barrier to gifting. It is a solvable problem, however; those who plan early and build a clear picture of their future financial needs are far better placed to gift with confidence, knowing what they can afford to give without compromising their own security and hopefully leaving less tax for their loved ones to pay on their death.
| Top barriers to early gifting | % |
|---|---|
| Running out of money later in retirement | 37.3% |
| Care home costs | 15.5% |
| No concerns | 15.0% |
| Money won’t be used responsibly | 11.5% |
| Inheritance tax concerns | 10.7% |
| Economic uncertainty | 4.7% |
| Family disputes | 2.3% |
What being unprepared actually costs
Delay becomes deputyship. Without a registered Lasting Power of Attorney, a family that needs to manage a loved one's finances or care decisions after they lose mental capacity has to apply to the Court of Protection instead. Registering an LPA in good time costs £92; applying for deputyship after capacity is lost costs £400 – before factoring in the months it can take to get a court order in place, during which bills, care fees and property costs still need to be paid. Over a million LPAs were registered with the Office of the Public Guardian in 2023–24, a rise of more than 30% since 2019–20, showing more people are waking up to this – but the majority still haven't.
No will means no control, and often, no speed
When someone dies without a valid will, their estate is distributed under intestacy rules, which take no account of unmarried partners, stepchildren, or personal wishes. It also tends to take longer: according to DNA Legal, the number of probate cases taking over a year to resolve has risen 518% in five years, from 377 in 2019 to 2,328 in 2024, as estates become more complex and more contested.
Being unmarried carries a real financial cost
This is an increasingly significant issue given the growth in cohabiting families, which now number around 3.5 million in 2025, more than double the figure 30 years ago. For cohabiting couples, the absence of a will could mean losing a home they've lived in for decades if it isn't owned on a joint tenancy basis. A recent government consultation, which closed on 14 August 2026, examined whether unmarried partners should gain automatic inheritance rights if their partner dies without a will – a sign of how significant a gap this has become, but a change that, if it happens at all, is still some way off. For now, the only real protection is a will, and ideally a cohabitation agreement, drawn up in advance.
Gifting that stalls costs the giver peace of mind and the recipient certainty
TPO’s survey found that among people who haven't yet gifted, 39.7% still intend to – but uncertainty about their own future costs, particularly care, is often what stops a gift from being made or completed, while it would still help most. A gift promised but never followed through leaves both generations in limbo: the older generation still carrying the asset (and the tax exposure) they meant to pass on, and the younger generation still without the support they thought they could expect.
Practical steps: what "prepared" actually looks like
None of this requires anything dramatic – just a small number of documents and decisions, made once and reviewed regularly.
- Make a will and review it after any major life event – moving house, starting a new relationship, the arrival of a child, or the death of someone close. This is the biggest single gap in UK planning and the easiest to plug. Free Wills Month is a UK campaign run twice a year, in March and October, giving people aged 55+ the chance to have a simple will written or updated by a solicitor free of charge.
- Register a Lasting Power of Attorney for both property and financial affairs and health and welfare while you have full capacity to do so. It's a fraction of the cost and the stress of a deputyship application made in a crisis.
- If you're cohabiting, don't rely on "common law marriage." A will that names your partner, and a cohabitation agreement setting out how shared assets are treated, are currently the only reliable protections.
- If you're planning to gift, plan the whole gift, not just the giving. Whether it's help with a deposit, a contribution to a pension, or money into a Junior ISA or trust for a grandchild, working out what you can afford to give, and keeping that separate from what you might need for your own care, turns a gift into a plan rather than a decision made under pressure. Don’t forget that if you can make use of the 7 year rule and/or gift money out of surplus income, this can reduce the IHT liability to your loved ones.
- Create a digital death file. A will and an LPA tell people what to do, but they still need to be able to find the accounts, documents and contacts to act on those wishes. A secure digital file, one that stores your will, any trust details, tax information, professional contacts and emergency details, and that trusted people know how to access, removes a significant burden from the people left behind. You can also name a digital executor in your will to give someone specific responsibility for managing online accounts and digital assets. Without one, families can be left chasing logins and account details at exactly the moment they are least equipped to do so. At The Private Office, all clients have access to TPO Wealth, a secure online portal that acts as a digital filing cabinet for exactly this purpose, at no additional cost.
- Talk to your family about what you've decided, not just to a solicitor. Most of the stress in these situations comes from people finding out too late, not from the decisions themselves.
- Be aware of changes we know are coming. From April 2027, unused pension funds will form part of your estate for inheritance tax purposes, which is precisely why being prepared matters. Not only is this likely to bring more people into the IHT trap - and subject some beneficiaries to income tax as well as IHT - but it will also increase the burden on executors, who will need to account for all pensions held at the time of death. Having your affairs in order, with clear records of every pension you hold, is no longer just good practice; it is something your loved ones will be grateful for. It’s also essential to review who you have nominated your pension to on your death, as the new rules could mean that you might want to change your mind.
Having Peace of Mind
The more assets a family has, the more moving parts there tend to be – pensions, property, trusts, gifting plans – and the more those decisions need to work together rather than being made one at a time.
Talking about what happens when we die is never easy, and it’s understandable that people put it off. But from our experience, the biggest cost of not having these conversations is not only the financial cost, but the additional stress and uncertainty placed on the people we leave behind.
When a family is already dealing with the loss of someone they love, having to untangle their financial affairs or discover that arrangements weren’t quite what they thought, can make an incredibly difficult time even harder.
The good news is that getting your affairs in order doesn’t have to be complicated. A valid will, appropriate powers of attorney, clear records of your finances and some thought about how and when you want to pass on your wealth can make a significant difference.
It’s also important to look at these things as part of one overall plan, rather than as isolated decisions. Taking a little time now to understand what you have, what you want to happen and what your family might need means you can make those decisions on your own terms, rather than leaving them to others at a much more difficult time.
If you're not sure where your own plans stand, or it's been a while since you looked at them, talk to one of our advisers about reviewing them.
*The findings are drawn from a survey of 2,126 The Private Office newsletter subscribers, conducted in May 2026. The sample is weighted heavily towards older, asset-rich homeowners, reflecting the demographic most likely to be engaged in intergenerational wealth transfer. Respondents skewed towards the 65 and over age group (77% of the sample), with 40.1% aged 65 to 74 and 36.9% aged 75 and over. The remaining respondents were aged 55 to 64 (18.2%), 45 to 54 (3.8%) and under 45 (1.0%). In terms of housing status, 91.3% were outright homeowners, 5.5% held a mortgage, 1.4% rented privately, and 1.8% fell into other categories. 75.3% of respondents had children, grandchildren, or both.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The information contained in this article is based on our understanding of legislation, whether proposed or in force, and market practice at the time of writing. Levels, bases and reliefs from taxation may be subject to change.
The Financial Conduct Authority (FCA) does not regulate cash flow planning, estate planning, tax or trust advice.
State Pension to be taxed following rise
The full State Pension is due to rise to above £13,000 a year, raising fresh questions about the growing cost of the system and fairness between generations.
Under the ‘triple lock’, payments rise by whichever is highest of average wage growth, inflation or 2.5%.
The latest figures from the Office for National Statistics (ONS) showed total wage growth, including bonuses, stood at 3.9% in the quarter to July, down from 4.2% in the three months to June. These earnings figures would mean the full, flat rate State Pension would increase by 3.9% or £488 next April to £13,036.40.
However, this won’t be locked in until the inflation figures for September are published in October, as they could in theory be higher than the 3.9% taken from total wage growth. The inflation figures for August were released on Wednesday, showing that inflation had risen to 3.1% in the 12 months to August, up from 2.9% in July.
The State Pension age is rising to 67 in April 2028, but government spending continues to increase. The annual State Pension bill is expected to reach £154bn this year and could rise by a further £600m a year by 2029/30 according to estimates.
Economists have raised concerns about the cost of the State Pension ahead of the Budget, as with this raise, pensioners are beating headline inflation at a time when many are struggling to keep pace, while pensioner groups argue that many older people still face poverty. Additionally, with this increase, the State Pension will breach the personal allowance threshold, making it in theory liable to be taxed.
The ‘Triple Lock’ explained
The ‘triple lock’ refers to a well-known State Pensions policy introduced in 2010 by the Conservative and Liberal Democrat Coalition Government that ensures State Pensions rise every year by either the average earnings growth, inflation (as measured by the Consumer Prices Index) or a flat 2.5% - whichever is highest that year, hence the name ‘triple’ lock.
It was designed in principle to make sure that State Pension value would always have the best growth outcome each year for pensioners. The guarantee that the highest of the three variables will be what pensions grow by ensures that Pensioners have three layers of protection against inflation, hence the name ‘triple lock’. This is incredibly important in maintaining a level of healthy financial security for those relying on their pensions, as it guarantees growth irrespective of how volatile the economy becomes.
If you want to find out more about retirement planning, why not give us a call on 0333 323 9065 or book a free non-committal initial consultation with one of our chartered financial advisers to find out how we might be able to help you.
Arrange a free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
Over a million pensioners pushed into higher rate tax
The number of pensioners paying higher rate tax has doubled in the past five years, according to a recent freedom of information (FOI) request from Sir Steve Webb, UK's former Minister of State for Pensions.
Now, over a million pensioners are paying higher rate tax or more this year, up from half a million in 2021-22, with the number of pensioners paying additional rate tax, a tax band originally intended for only the highest earners in society, having trebled during the same timeframe.
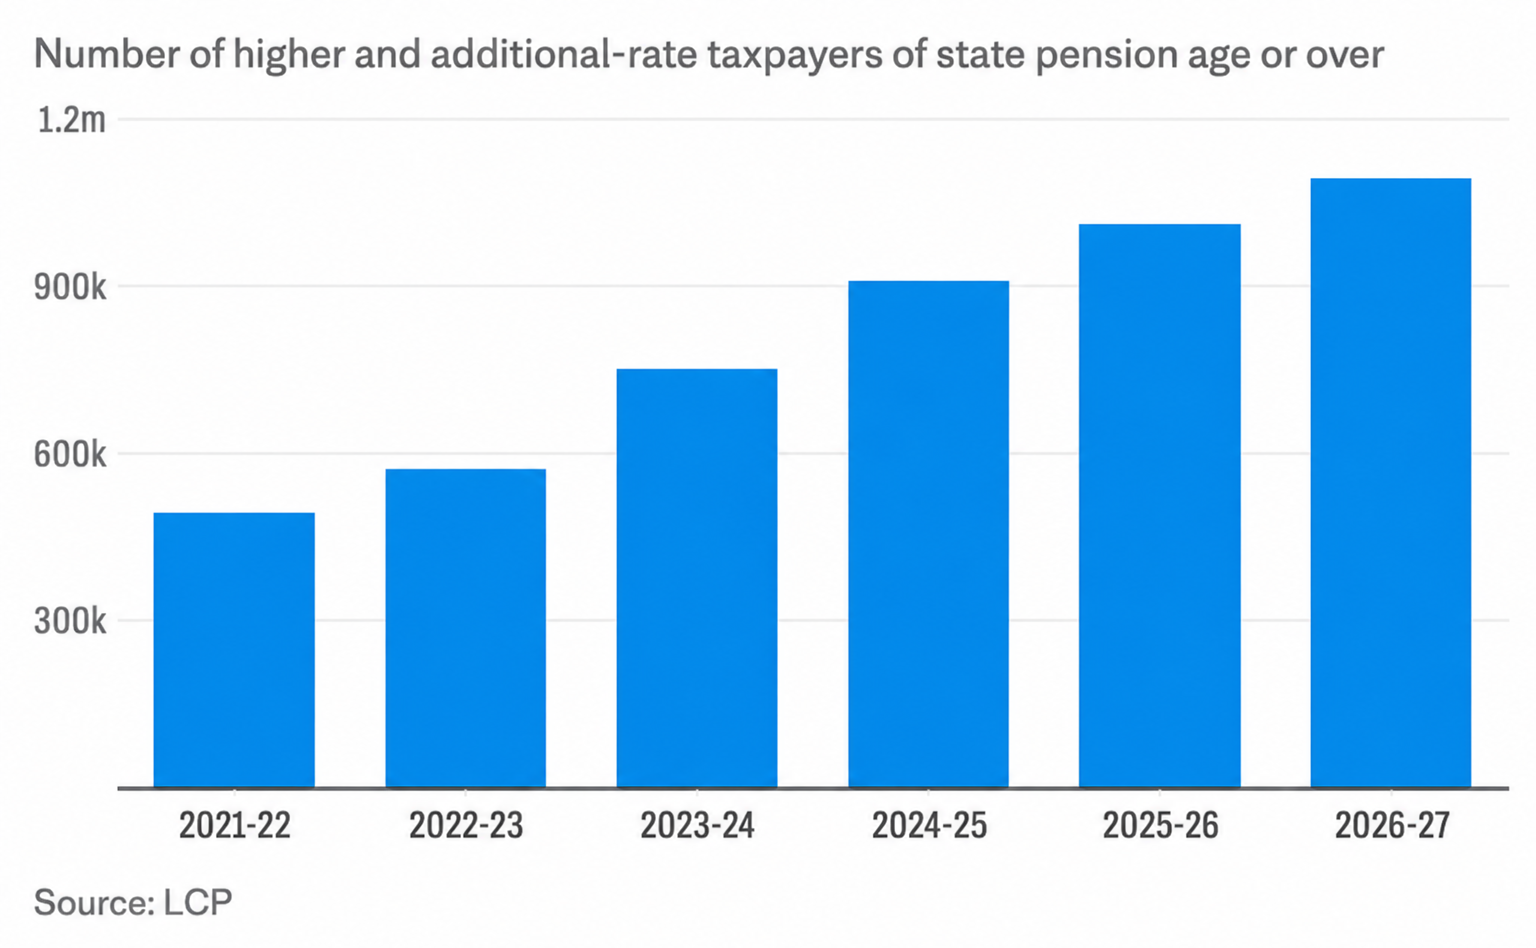
Once again, frozen thresholds or ‘stealth taxes’ are at the root of the issue, as the net widens, capturing more pensioners in the higher rate tax bands. According to the FOI data, the number of pensioners paying higher and additional rates of income tax has risen as state pension incomes increase in line with inflation while income tax thresholds remain frozen.
With thresholds set to stay at their current levels until April 2031, more retirees are likely to find that growing state and private pension income takes them into higher tax bands.
As this continues, it is likely to affect retirement planning for many workers. If a greater share of pension income is lost to tax, people may need to build up larger pension pots and savings during their working lives to achieve the level of income they want in retirement.
Arrange a free initial consultation
The forever frozen allowances
It has become the new norm for each Government to announce a further freeze on allowances, kicking the can down the road with each successive freeze, all the while taxpayers are being forced to hand over increasing amounts as fiscal drag pulls them ever further beyond the outdated thresholds.
One example of this is inheritance tax (IHT). Total IHT receipts collected by the Government has been steadily on the rise since the IHT threshold freeze.
This was initially announced by the then Chancellor, Rishi Sunak, in his 2021 Budget. The Budget outlined that the IHT threshold would be frozen for five years until 2026. However, after ex-Chancellor Jeremy Hunt’s 2023 Autumn Statement, it was confirmed that the freeze would be extended a further two years until April 2028, and then after Rachel Reeves’ 2024 Autumn Statement, this was extended once again a further two years until April 2030, and finally after her 2025 Autumn budget, it was again extended, this time until April 2031.
Many have been calling this move an example of ‘stealth tax’, as the freeze ultimately means an increasing number of Britons will fall into the tax threshold each year until the freeze ends in April 2031 – if indeed it does end and hasn’t been extended again by that time – and by then the Government will have collected billions of pounds worth of extra IHT from the taxpayer.
If you want to find out more, why not give us a call on 0333 323 9065 or book a free non-committal initial consultation with one of our chartered advisers to find out how can help.
Arrange a free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate tax advice.
A pension is a long-term investment not normally accessible until age 55 (57 from April 2028 unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up which would have an impact on the level of pension benefits available.
Your pension income could also be affected by the interest rates at the time you take your benefits. The tax implications of pension withdrawals will be based on your individual circumstances, tax legislation and regulation which are subject to change. You should seek advice to understand your options at retirement.
Families hit by inheritance tax on pensions
From next April, grieving families will not only be taxed on their loved one’s pensions, but will also be prevented from claiming loss reliefs on those pension pots under new planned taxation rules.
Under these plans, estates could face higher tax bills and extra late payment interest at the worst possible time while dealing with a bereavement.
Previously, pension pots were exempt from inheritance tax (IHT) and not included in the taxable estate after someone died, but following an announcement last year from former chancellor Rachel Reeves, pension pots will now be included in an individual’s estate from April 2027, meaning they will be subject to IHT on death like any other part of an estate.
Currently, if an asset is sold at a loss within 12 months of the death, family members are entitled to reclaim the difference in tax from HM Revenue & Customs (HMRC) through “loss on sale relief”. However, the same rule will not apply to pensions if they fall in value.
HMRC confirmed that certain IHT reliefs will not apply to unused pension assets as the deceased isn’t classed as owning the assets before death, despite being taxed like the rest of the estate. Executors will be unable to claim loss on sale relief, business property relief, agricultural property relief or pay inheritance tax by instalments on qualifying pension assets, despite those reliefs remaining available for assets held outside pensions.
There is concern that this could create a 'two-tier' system, where pensions will have less protections from tax.
What is inheritance tax?
Inheritance Tax (IHT) is a tax levied by the Government on the estate of a deceased person in the UK. This covers all of their assets including property, personal belongings, investments and, from April 2027, it also includes pensions.
However, this levy only applies to the total value of the estate that exceeds the IHT threshold or ‘nil-rate band’. As of the 2025/26 tax year, the threshold is set at £325,000. Anything above £325,000 could be subject to up to 40% inheritance tax and anything below this threshold is tax-free. In addition, an extra allowance known as the residence nil rate band (RNRB) of up to £175,000 may apply when a main home is passed to direct descendants, potentially increasing the total tax-free threshold to £500,000 for an individual.
Traditionally pensions have been exempt from inheritance tax but, from April 2027, pensions will no longer have this exempt status. This means that inheritance tax may have to be paid on your pension when you die.
If you’re interested in how to manage your inheritance tax to ensure the best possible wealth protection for you or your family, we can help. Give us a call on 0333 323 9065 or book a free non-committal initial consultation with a member of our team to find out more.
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate tax advice.
A pension is a long-term investment not normally accessible until age 55 (57 from April 2028 unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up which would have an impact on the level of pension benefits available.
The Stealth Tax Squeeze
A new report has highlighted the growing impact of frozen tax allowances in the UK, with some thresholds remaining unchanged for more than four decades.
Research from Association of Taxation Technicians (ATT) found that numerous allowances have remained static for decades, resulting in taxpayers paying more in real terms without any formal increase in tax rates – a policy by the Government known more informally as ‘stealth tax’.
ATT argues that many tax reliefs are overdue a comprehensive review, as years of inflation have steadily reduced their real-world value through fiscal drag.
So, who’s being affected by ‘stealth taxes’?
Almost everyone will in some way or another be losing money to stealth taxes.
Inheritance tax provides some of the clearest examples. The nil-rate band, which determines how much of an estate can be passed on free from inheritance tax, currently remains at £325,000 per individual. This threshold was last increased 17 years ago and is now scheduled to stay frozen until 2031. According to the ATT report, if it had been adjusted in line with inflation, it would stand at approximately £525,000 today, around 60 per cent higher than its current level.
The same pattern can be seen across other inheritance tax exemptions. The annual gifting allowance has been fixed at £3,000 since 1981. Using the Bank of England’s inflation calculator, the ATT estimates that an inflation-linked equivalent would now be around £11,800, almost four times the existing allowance.
Meanwhile, the wedding gift exemption has remained unchanged at £5,000 since 1975, having originally been introduced under the capital transfer tax regime before inheritance tax existed in its current form. Had it increased in line with inflation over that period, it would now be worth £39,876, representing a rise of 697 per cent. With UK weddings in 2026 costing on average an eye watering £20,604, that missed 697 per cent will come with an especially nasty sting for newly weds.
The report also found that savers have been affected by the same phenomenon. Basic-rate taxpayers can currently receive up to £1,000 of savings interest tax-free under the personal savings allowance, while higher-rate taxpayers are entitled to £500. Had these limits risen alongside inflation since their introduction in 2016, they would now be worth roughly £1,400 and £700 respectively.
Homeowners benefiting from the Rent a Room scheme have also seen the value of their tax break eroded. The scheme's £7,500 tax-free income limit has not increased since 2016. If it had kept pace with inflation, it would now be closer to £10,500.
Not even those saving into their pensions have been able to escape the stealth tax net. Individuals without relevant earnings can contribute £2,880 each year to a pension, which becomes £3,600 after tax relief is added. This allowance has remained unchanged since 2000. If uprated for inflation, it would be approximately £5,500 net, or £6,850 including tax relief.
The forever frozen allowances
It has become the new norm for each Government to announce a further freeze on allowances, kicking the can down the road with each successive freeze, all the while taxpayers are being forced to hand over increasing amounts as fiscal drag pulls them ever further beyond the outdated thresholds.
One example of this is inheritance tax (IHT). Total IHT receipts collected by the Government has been steadily on the rise since the IHT threshold freeze.
This was initially announced by the then Chancellor, Rishi Sunak, in his 2021 Budget. The Budget outlined that the IHT threshold would be frozen for five years until 2026. However, after ex-Chancellor Jeremy Hunt’s 2023 Autumn Statement, it was confirmed that the freeze would be extended a further two years until April 2028, and then after Rachel Reeves’ 2024 Autumn Statement, this was extended once again a further two years until April 2030, and finally after her 2025 Autumn budget, it was again extended, this time until April 2031.
Many have been calling this a clear example of stealth taxes, as the freeze ultimately means an increasing number of Britons will fall into the tax threshold each year until the freeze ends in April 2031 – if it indeed does end and hasn’t been extended again by that time – and by then the Government will have collected billions of pounds worth of extra IHT from the taxpayer.
If you want to find out more, why not give us a call on 0333 323 9065 or book a free non-committal initial consultation with one of our chartered financial advisers to find out how can help.
Arrange a free initial consultation
The Financial Conduct Authority (FCA) does not regulate cash flow planning, tax or estate planning.
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The information contained in this article is based on our understanding of legislation, whether proposed or in force, and market practice at the time of writing. Levels, bases and reliefs from taxation may be subject to change.
